Eugen Soloviov
Trading-systems engineer
Trading-systems engineer building bots since 2017: cross-exchange arbitrage (connected up to 30 venues), cointegration-based pairs arbitrage across spot and futures, scalping, news and sentiment-driven strategies, trend algorithms, and portfolio management and balancing algorithms. Also builds sub-millisecond order execution, big-data warehouses, backtesting engines, AI agents, and trading interfaces (incl. open-source profitmaker.cc). Stack: JS/TS, Python, Rust/Zig/Go, DevOps, backend, frontend, architecture.
Articles
रणनीतियों के लिए केली क्राइटेरियन: पोजीशन साइज़िंग और पूंजी आवंटन कैसे करें
पॉज़िटिव एक्सपेक्टेड वैल्यू वाली रणनीति भी अगर बेट साइज़ गलत हो तो आपका अकाउंट उड़ा सकती है। हम केली क्राइटेरियन को फॉर्मूला की व्युत्पत्ति से लेकर रणनीतियों के पोर्टफोलियो तक समझते हैं: फुल केली क्यों खतरनाक है, फ्रैक्शनल केली आधी वोलैटिलिटी में 75% ग्रोथ कैसे देता है, और एक इंटरैक्टिव कैलकुलेटर जो दिखाता है कि केली फ्रैक्शन रिटर्न और रिस्क को कैसे बदलता है।
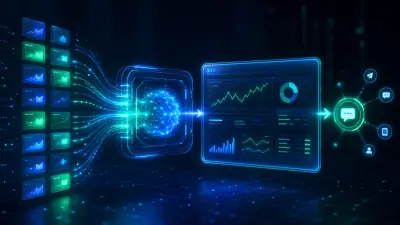
Daily Stock Analysis: एक AI सिस्टम जो वॉचलिस्ट को रोज़ाना निर्णय डैशबोर्ड में बदल देता है
ZhuLinsen के daily_stock_analysis का गहन विश्लेषण — एक ओपन-सोर्स सिस्टम जो A-शेयर, हॉन्ग कॉन्ग, अमेरिका और अन्य बाज़ारों का डेटा लाता है, LLM के ज़रिए तकनीकी और समाचार विश्लेषण चलाता है, और हर ट्रेडिंग दिन आपके मैसेंजर पर एक संरचित 'डिसीज़न डैशबोर्ड' भेजता है। आर्किटेक्चर, डेटा फ़ॉलबैक, एजेंट रणनीतियाँ, सीमाएँ।
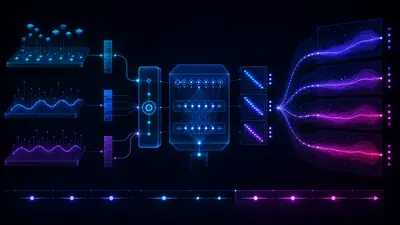
Temporal Fusion Transformers for Multi-Horizon Portfolio Forecasting
How Google's Temporal Fusion Transformer brings interpretable multi-horizon forecasting to quantitative portfolio management, with attention-based variable selection, quantile outputs, and a worked pytorch-forecasting pipeline.
जोखिम-सजग पोज़िशन साइज़िंग के लिए कॉन्फ़ॉर्मल प्रेडिक्शन
गारंटीशुदा कवरेज के साथ वितरण-मुक्त भविष्यवाणी अंतराल। हम split conformal, jackknife+ और adaptive conformal inference का उपयोग करके ट्रेडिंग जोखिम को कैलिब्रेट करते हैं और बिना पैरामीट्रिक मान्यताओं के पोज़िशन का आकार तय करते हैं।
Bid-Ask Spread Modeling and Prediction with Machine Learning
Decomposing and predicting bid-ask spreads with ML — from Roll's implicit estimator to gradient boosting and neural networks — with the units, leakage, and benchmarking pitfalls that bite in production.
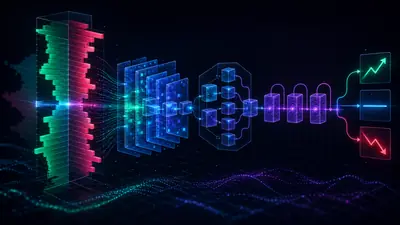
DeepLOB: लिमिट ऑर्डर बुक्स पर डीप लर्निंग
DeepLOB कैसे एक CNN, एक इंसेप्शन मॉड्यूल और एक LSTM को मिलाकर कच्चे ऑर्डर बुक डेटा से मिड-प्राइस मूवमेंट का अनुमान लगाता है — आर्किटेक्चर, असली FI-2010 आंकड़े, और एक कार्यशील PyTorch पुनर्कार्यान्वयन।
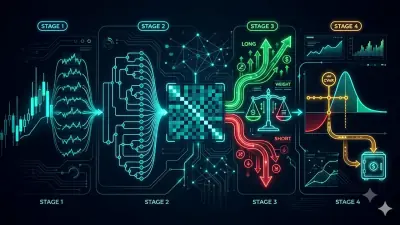
हमारे घरेलू एल्गोरिद्म के भीतर: Hull-White के साथ HRP + Long/Short + CVaR
Pipeline की गहराई से पड़ताल — वह समग्र एलोकेशन एल्गोरिद्म जिसे हमने HRP के ऊपर बनाया। आधार के रूप में Hierarchical Risk Parity, एजेंट सिग्नल और कॉन्फिडेंस से संचालित एक long/short ओवरले, और Hull-White वोलैटिलिटी एडजस्टमेंट के साथ CVaR के जरिए अंतिम रिस्क करेक्शन। हमारे स्पेक की पूरी गणित, साथ ही असली Rust इम्प्लीमेंटेशन।
12 पोर्टफोलियो ऑप्टिमाइज़ेशन एल्गोरिदम की तुलना: HRP, Black-Litterman, NCO और आगे
क्रिप्टो की एक टोकरी, बारह आवंटन एल्गोरिदम, एक ईमानदार तुलना। हमने एक ओपन-सोर्स Rust पोर्टफोलियो ऑप्टिमाइज़र जारी किया है जो एक ही इंटरफ़ेस के पीछे HRP, HERC, MVO, Black-Litterman, NCO, Entropy Pooling और अन्य को चलाता है — यहां बताया गया है कि हर एक कैसे सोचता है और क्यों कोई एक विजेता नहीं है।
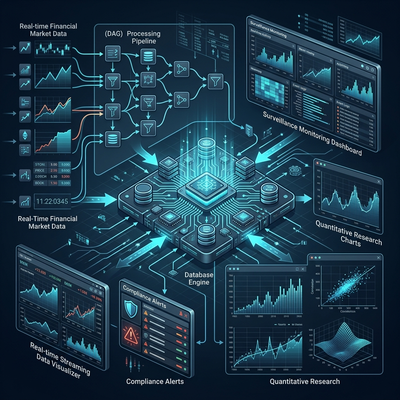
OneTick: वह प्लेटफ़ॉर्म जहाँ एक्सचेंज स्पूफर्स को पकड़ते हैं और हेज फंड अल्फा की तलाश करते हैं
OneTick की आर्किटेक्चर — टिक डेटा के लिए एक एंटरप्राइज़-ग्रेड टाइम-सीरीज़ इंजन। Event Processors के ज़रिए DAG queries, एकीकृत रीयल-टाइम और हिस्टोरिकल डेटा, मार्केट सर्विलांस (MiFID II, MAR, SEC), TCA, क्वांट रिसर्च और kdb+ से तुलना।
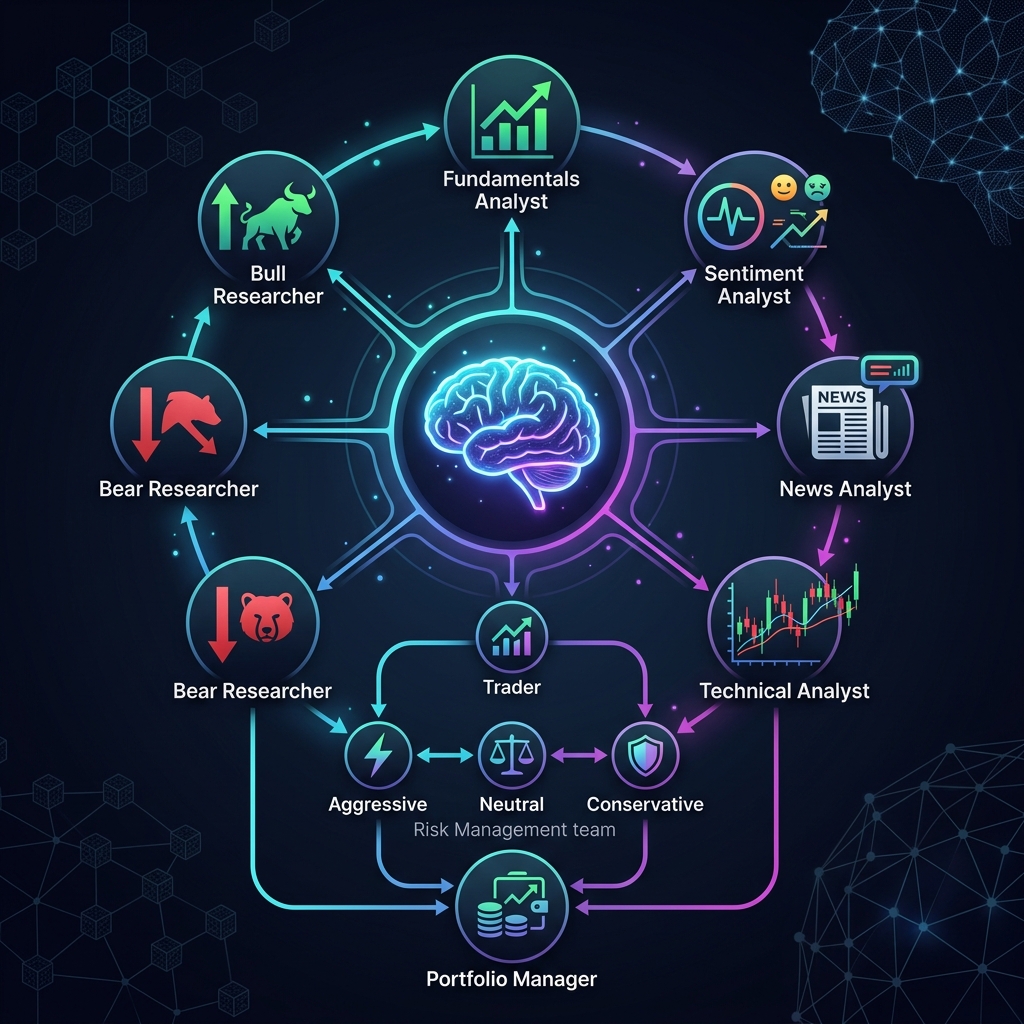
TradingAgents: Multi-Agent AI Framework That Models a Hedge Fund
Architecture deep dive into TradingAgents — an open-source LangGraph framework where LLM agents (analysts, researchers, trader, risk management, portfolio manager) engage in structured debates to make trading decisions.
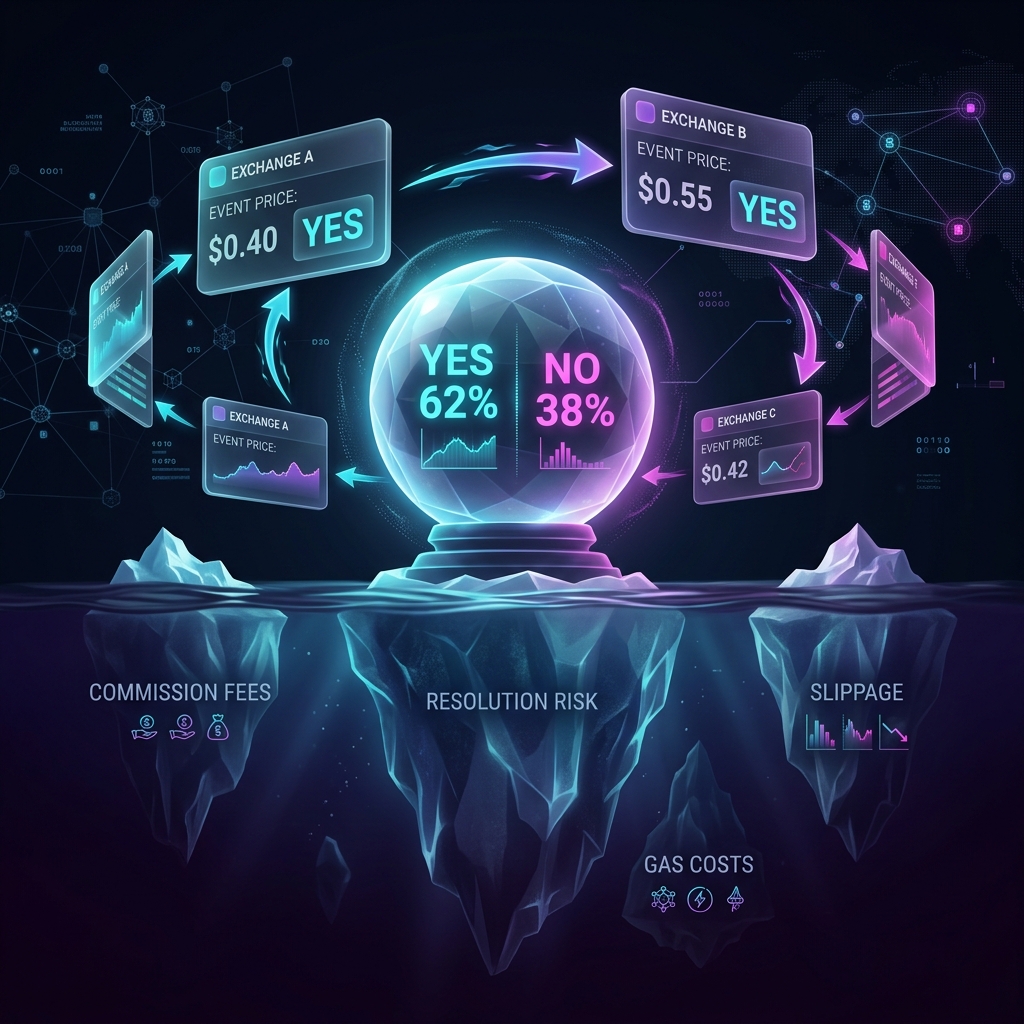
प्रेडिक्शन मार्केट आर्बिट्राज: छिपी लागतें, फीस और असली गणित
Polymarket, Limitless, Predict.fun, Opinion और Kalshi के बीच आर्बिट्राज का विश्लेषण। डायनामिक फीस, क्रॉस-चेन ब्रिज, स्लिपेज, रिज़ॉल्यूशन रिस्क — और क्यों 5% का स्प्रेड भी घाटे में जा सकता है।
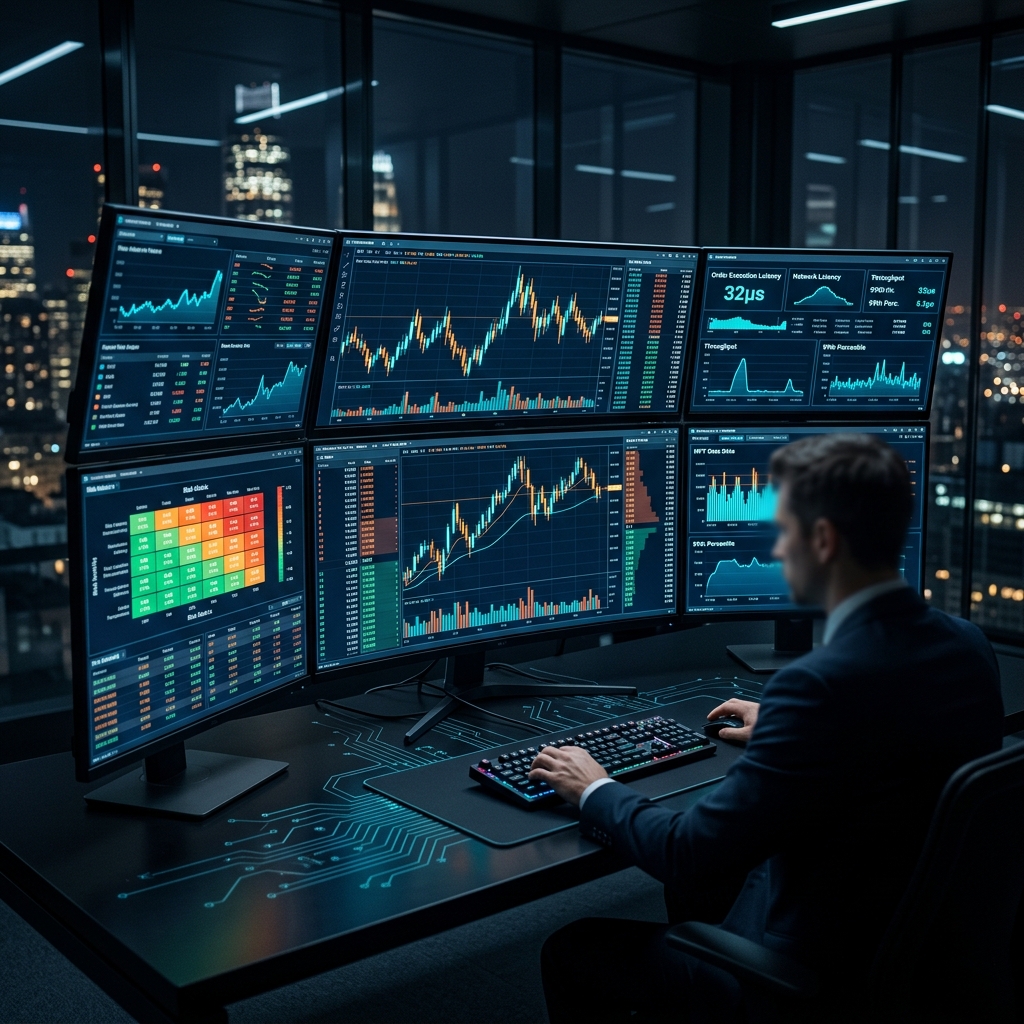
T-Bricks (Broadridge): How the Platform Powering Prop Firms Works
Architecture of T-Bricks — a modular HFT platform in C++ for market making, ETF arbitrage, and centralized risk management. 100+ clients, 150+ exchanges, nanosecond latencies.