Statistical Arbitrage & Pairs Trading
Trade the spread between correlated assets — from the distance approach to cointegration and Kalman filters, then dynamically combining mean reversion with momentum.
- 01
 May 21, 2025#pairs-trading
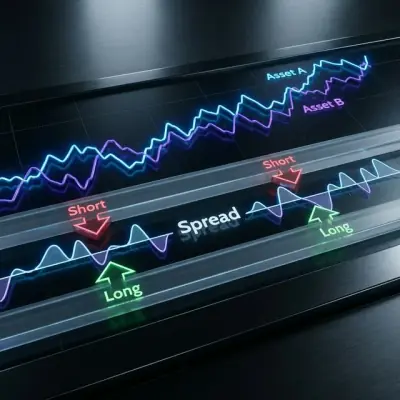
Distance Approach in Pairs Trading: Implementation and Analysis with Rust
A comprehensive analysis of basic and advanced Distance Approach methodologies for pairs trading, with practical implementations in Rust tailored for high-frequency traders and algorithmic developers.
- 02
 Mar 19, 2026#stat arb
Statistical Arbitrage and Pairs Trading in Crypto Markets: From Cointegration to the Kalman Filter
A complete guide to statistical arbitrage for crypto markets. Cointegration, Kalman filter, basis strategies, cross-exchange arbitrage. With backtests and Python code.
- 03
 Mar 14, 2026#algotrading
Signal Correlation: How Many Pairs to Monitor
Why 10 crypto pairs don't provide 10x diversification, how to calculate effective_N via correlation_factor, and how many pairs you really need to monitor for 80-90% orchestrator slot utilization.
- 04
 May 21, 2025#statistical arbitrage
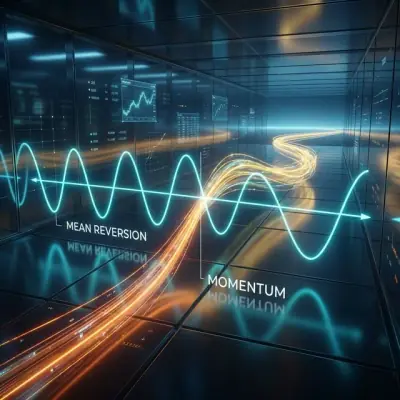
Dynamically Combining Mean Reversion and Momentum Strategies in Statistical Arbitrage: Mathematical Foundations and Practical Implementation
An advanced exploration of how to integrate mean reversion and momentum strategies in statistical arbitrage using PCA-based signal decomposition, regime-switching models, and dynamic portfolio optimization.
- 05
 Mar 5, 2026#algo trading
Funding Rate Arbitrage Across Exchanges: How to Profit from Rate Differences
How funding rate arbitrage works across crypto exchanges, why rates differ on Binance, Bybit, OKX and dYdX, and how to build a monitoring and execution system to extract profit from these discrepancies.