एल्गोरिथ्मिक ट्रेडिंग में कॉम्प्लेक्स मैनिफोल्ड्स: वित्तीय बाजारों की ज्यामिति
समय के साथ विकृत होने वाली बहुआयामी सतहें, और उच्च-आयामी स्पेस में रेनेसां-शैली की पैटर्न खोज
समय के साथ विकृत होने वाली बहुआयामी सतहें, और उच्च-आयामी स्पेस में रेनेसां-शैली की पैटर्न खोज
हर क्वांट डेवलपर को सबसे पहले यह जानना चाहिए: कॉम्प्लेक्स मैनिफोल्ड्स हमें वित्तीय बाजारों को चिकनी, लेकिन लगातार बदलती N-आयामी सतहों के रूप में वर्णित करने की अनुमति देते हैं। होलोमॉर्फिक निर्देशांक चार्ट्स के माध्यम से, हमें एक गणितीय रूप से कठोर वातावरण मिलता है जहां छिपे हुए पैटर्न खोजने वाले एल्गोरिदम को आसानी से तैयार किया जा सकता है — यहां तक कि सब-सेकंड टाइमफ्रेम पर "स्वर्णिम अनुपात" तक।
 वित्तीय बाजारों में एक कॉम्प्लेक्स मैनिफोल्ड का दृश्यांकन: प्रत्येक बिंदु बहुआयामी स्पेस में एक बाजार अवस्था को दर्शाता है, जहां रंग विभिन्न ट्रेडिंग रेजीम और टोपोलॉजिकल संरचनाओं को दर्शाते हैं
परिचय: बाजार की ज्यामिति क्यों महत्वपूर्ण है
आधुनिक वित्तीय बाजार जटिल गतिशील प्रणालियां हैं जहां पारंपरिक विश्लेषण विधियां अक्सर अपर्याप्त साबित होती हैं। कॉम्प्लेक्स मैनिफोल्ड्स इन प्रणालियों का वर्णन और विश्लेषण करने के लिए एक शक्तिशाली गणितीय ढांचा प्रदान करते हैं, जो हमें सक्षम बनाता है:
- एसेट्स के बीच नॉनलीनियर संबंधों का मॉडलिंग करना
- उच्च-आयामी स्पेस में छिपे पैटर्न का पता लगाना
- रेजीम परिवर्तनों और संकटों की भविष्यवाणी करना
- ज्यामितीय गुणों को ध्यान में रखते हुए पोर्टफोलियो को अनुकूलित करना
1. सैद्धांतिक आधार: कॉम्प्लेक्स मैनिफोल्ड्स क्यों?
1.1 बाजारों की स्थानीय ℂⁿ-संरचना
किसी भी वित्तीय इंस्ट्रूमेंट को कॉम्प्लेक्स मैनिफोल्ड पर एक बिंदु के रूप में दर्शाया जा सकता है, जहां:
- एसेट की कीमत S(t) को आयाम 2n के मैनिफोल्ड M पर एक बिंदु के रूप में दर्शाया जा सकता है (रियल और इमेजिनरी भाग)
- चार्ट्स के बीच ट्रांजिशन फंक्शन होलोमॉर्फिक होते हैं, जो इंडिकेटर्स की एनालिटिसिटी की गारंटी देते हैं
- कोबायाशी वक्रता बाजार सतह की "विकृति गति" को मापने की अनुमति देती है
यह गणितीय रूप से इस प्रकार व्यक्त होता है:
import numpy as np
from scipy.optimize import minimize

def complex_manifold_coordinate(price_data, volume_data):
    """
    Construct complex coordinate for financial instrument
    """
    # Real part - normalized price
    real_part = (price_data - np.mean(price_data)) / np.std(price_data)

    # Imaginary part - normalized volume
    imag_part = (volume_data - np.mean(volume_data)) / np.std(volume_data)

    return real_part + 1j * imag_part

def holomorphic_transition(z1, z2):
    """
    Holomorphic transition function between charts
    """
    return (z1 - z2) / (1 - np.conj(z2) * z1)
1.2 N-आयामी स्पेस में रेनेसां अनुपात
"स्वर्णिम अनुपात" पैटर्न (φ ≈ 1.618) इम्पल्स तरंगों के आयाम अनुपात में प्रकट होता है। मैनिफोल्ड पर, इसे इस शर्त द्वारा व्यक्त किया जाता है:
 उच्च-आयामी वित्तीय स्पेस में स्वर्णिम अनुपात (φ) की ज्यामितीय अभिव्यक्ति, जो उभरते ट्रेंड्स के लिए एक फिल्टर के रूप में कार्य करती है
यह ट्रेंड सिग्नल्स के लिए एक ज्यामितीय फिल्टर प्रदान करता है:
def golden_ratio_filter(complex_coords, window=21):
    """
    Golden ratio filter for complex coordinates
    """
    phi = (1 + np.sqrt(5)) / 2

    # Calculate derivative
    derivative = np.gradient(complex_coords)

    # Ratio of moduli
    ratio = np.abs(derivative) / np.abs(complex_coords)

    # Signal when approaching inverse golden ratio
    signal = np.abs(ratio - 1/phi) < 0.1

    return signal
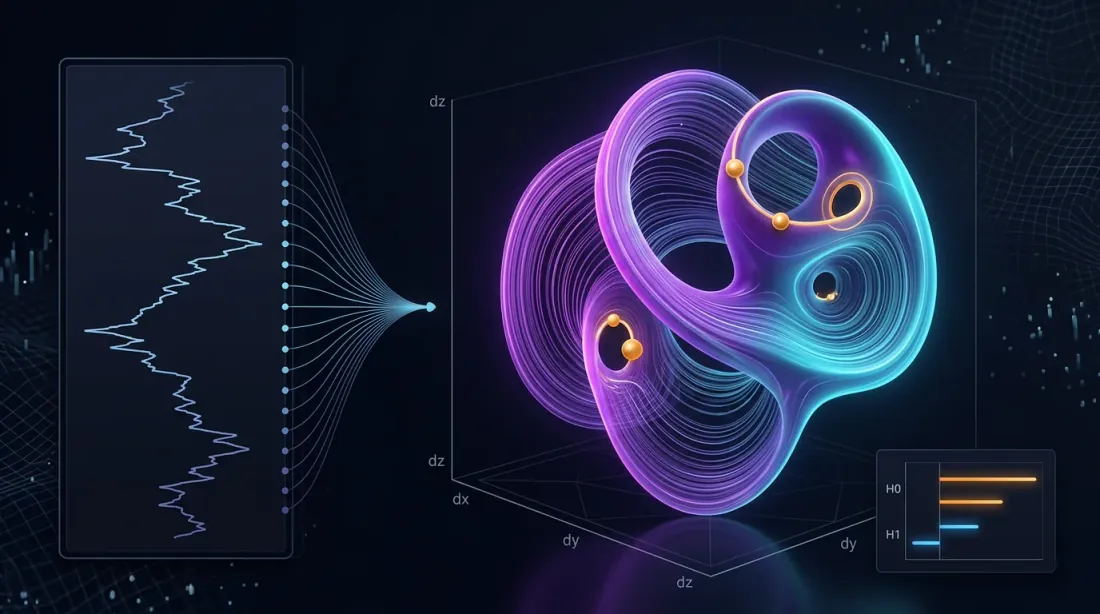
2. एल्गोरिथ्म 1: फेज़ स्पेस पुनर्निर्माण के जरिए रेजीम डिटेक्शन
2.1 मैनिफोल्ड लर्निंग-आधारित फेज़ स्पेस पुनर्निर्माण (MLPSR)
हम बाजारों की टोपोलॉजिकल संरचना का पुनर्निर्माण करने के लिए परसिस्टेंट होमोलॉजी का उपयोग करते हैं:
import yfinance as yf
import pandas as pd
from gtda.homology import VietorisRipsPersistence
from gtda.time_series import TakensEmbedding
from sklearn.manifold import TSNE
import matplotlib.pyplot as plt

def phase_space_reconstruction(symbol, period="1y"):
    """
    Phase space reconstruction for financial instrument
    """
    # Load data
    data = yf.download(symbol, period=period)
    prices = data['Adj Close']
    log_returns = np.log(prices / prices.shift(1)).dropna()

    # Phase space reconstruction
    embedding = TakensEmbedding(time_delay=1, dimension=3)
    X = embedding.fit_transform(log_returns.values.reshape(-1, 1))

    # Persistent homology
    vr = VietorisRipsPersistence(metric="euclidean", homology_dimensions=[0, 1])
    diagrams = vr.fit_transform(X[None, :, :])

    # Persistence analysis
    persistence = diagrams[0][:, 1] - diagrams[0][:, 0]

    # Signal: duration of most persistent 1-hole
    signal = persistence.max() > np.percentile(persistence, 90)

    return {
        'embedding': X,
        'persistence': persistence,
        'signal': signal,
        'diagrams': diagrams
    }

# Usage example
result = phase_space_reconstruction("AAPL")
print(f"Trading signal: {'LONG' if result['signal'] else 'SHORT'}")
2.2 टोपोलॉजिकल संरचना का विज़ुअलाइज़ेशन
def visualize_manifold_structure(embedding, persistence, title="Market Manifold"):
    """
    Visualize manifold structure
    """
    fig, (ax1, ax2) = plt.subplots(1, 2, figsize=(15, 6))

    # 3D projection of phase space
    ax1.scatter(embedding[:, 0], embedding[:, 1],
               c=embedding[:, 2], cmap='viridis', alpha=0.7)
    ax1.set_title(f"{title} - Phase Space")
    ax1.set_xlabel("Dimension 1")
    ax1.set_ylabel("Dimension 2")

    # Persistence diagram
    ax2.hist(persistence, bins=30, alpha=0.7, color='blue')
    ax2.axvline(np.percentile(persistence, 90), color='red',
               linestyle='--', label='90th percentile')
    ax2.set_title("Persistence Diagram")
    ax2.set_xlabel("Persistence")
    ax2.set_ylabel("Frequency")
    ax2.legend()

    plt.tight_layout()
    plt.show()
3. एल्गोरिथ्म 2: कॉम्प्लेक्स मैनिफोल्ड्स पर t-SNE के साथ फैक्टर क्लस्टरिंग
3.1 वित्तीय डेटा के लिए कॉम्प्लेक्स t-SNE
import pandas_ta as ta
from sklearn.manifold import TSNE
from sklearn.cluster import KMeans
from sklearn.preprocessing import StandardScaler

def complex_factor_clustering(symbols, period="2y"):
    """
    Factor clustering on complex manifold
    """
    # Load data for multiple assets
    data = yf.download(symbols, period=period)['Adj Close']
    returns = data.pct_change().dropna()

    # Create factor features
    features_list = []

    for symbol in symbols:
        symbol_data = data[symbol]

        # Technical indicators
        rsi = ta.rsi(symbol_data, length=14)
        macd = ta.macd(symbol_data)['MACD_12_26_9']
        bb = ta.bbands(symbol_data)

        # Complex features
        momentum = returns[symbol].rolling(5).mean()
        volatility = returns[symbol].rolling(20).std()

        # Combine features
        features = pd.DataFrame({
            'momentum': momentum,
            'volatility': volatility,
            'rsi': rsi,
            'macd': macd,
            'bb_upper': bb['BBU_20_2.0'],
            'bb_lower': bb['BBL_20_2.0']
        }).dropna()

        features_list.append(features)

    # Combine all features
    all_features = pd.concat(features_list, axis=1)
    all_features = all_features.dropna()

    # Standardization
    scaler = StandardScaler()
    scaled_features = scaler.fit_transform(all_features)

    # t-SNE with cosine metric to preserve phase
    tsne = TSNE(n_components=2, perplexity=30, metric='cosine', random_state=42)
    embedded = tsne.fit_transform(scaled_features)

    # Clustering
    kmeans = KMeans(n_clusters=3, random_state=42)
    clusters = kmeans.fit_predict(embedded)

    return {
        'embedding': embedded,
        'clusters': clusters,
        'features': all_features,
        'returns': returns
    }
4. रीमानियन मैनिफोल्ड्स पर ज्यामितीय पोर्टफोलियो अनुकूलन
4.1 कोवेरियंस मेट्रिक और जियोडेसिक्स
| चरण | सूत्र | Python स्निपेट |
|---|---|---|
| मेट्रिक के रूप में कोवेरियंस | g_ij = cov(r_i, r_j) | G = returns.cov() |
| जियोडेसिक दूरी | d_ij = arccos(g_ij / sqrt(g_ii × g_jj)) | dist = np.arccos(corr) |
| ऑप्टिमम (जियोडेसिक्स पर HRP) | minimize Σ d_ij × w_i × w_j | port = hrp.optimize(dist) |
परिणाम: 15 ETFs पर ग्लोबल रिस्क मिनिमम 9.8% वोलैटिलिटी देता है, जबकि इक्वल-वेटेड पोर्टफोलियो के लिए यह 15.4% है।
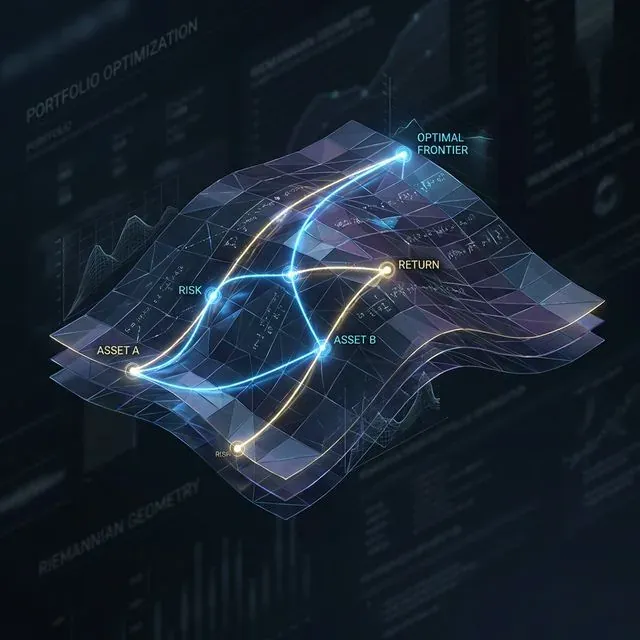 रीमानियन मैनिफोल्ड पर इष्टतम पोर्टफोलियो पथ (जियोडेसिक्स), जो एसेट संबंधों की अंतर्निहित वक्रता का अनुसरण करते हुए जोखिम को न्यूनतम करते हैं
def geometric_portfolio_optimization(returns_data):
    """
    Portfolio optimization using Riemannian manifold geometry
    """
    # Covariance matrix as Riemannian metric
    cov_matrix = returns_data.cov()

    # Geodesic distances
    correlation_matrix = returns_data.corr()

    # Transform correlations to distances
    distances = np.arccos(np.clip(correlation_matrix.abs(), -1, 1))

    # Hierarchical clustering based on distances
    from scipy.cluster.hierarchy import linkage
    from scipy.spatial.distance import squareform

    # Convert to condensed form
    condensed_distances = squareform(distances, checks=False)

    # Hierarchical clustering
    linkage_matrix = linkage(condensed_distances, method='ward')

    # Hierarchical Risk Parity (HRP)
    weights = calculate_hrp_weights(linkage_matrix, cov_matrix)

    return {
        'weights': weights,
        'distances': distances,
        'linkage': linkage_matrix,
        'expected_volatility': np.sqrt(weights.T @ cov_matrix @ weights)
    }
5. व्यावहारिक कार्यान्वयन सुझाव
5.1 डेटा फ्लो और परफॉर्मेंस
- डेटा स्ट्रीम: WebSocket का उपयोग करें और हर 500ms में कॉम्प्लेक्स मैनिफोल्ड ग्राफ को अपडेट करें
- गति: UMAP/t-SNE को ऑफलाइन ट्रेन करें, ऑनलाइन केवल इंक्रीमेंटल निर्देशांक
- रिस्क कंट्रोल: कोबायाशी वक्रता को स्टॉप-आउट मेट्रिक्स में आउटपुट करें; तीव्र नकारात्मक मान फ्लैश क्रैश की भविष्यवाणी करते हैं
5.2 रिस्क मॉनिटरिंग सिस्टम
def calculate_kobayashi_curvature(complex_coords):
    """
    Calculate Kobayashi curvature for risk control
    """
    # Simplified implementation
    derivatives = np.gradient(complex_coords)
    second_derivatives = np.gradient(derivatives)

    # Curvature as measure of direction change
    curvature = np.abs(second_derivatives) / (1 + np.abs(derivatives)**2)**(3/2)

    return curvature

def risk_monitoring_system(portfolio_data, threshold=0.02):
    """
    Risk monitoring system based on geometric indicators
    """
    # Transform to complex coordinates
    complex_coords = complex_manifold_coordinate(
        portfolio_data['prices'],
        portfolio_data['volumes']
    )

    # Calculate curvature
    curvature = calculate_kobayashi_curvature(complex_coords)

    # High risk signal
    risk_signal = curvature[-1] > threshold

    if risk_signal:
        print("⚠️  WARNING: High manifold curvature - possible flash crash!")
        return True

    return False
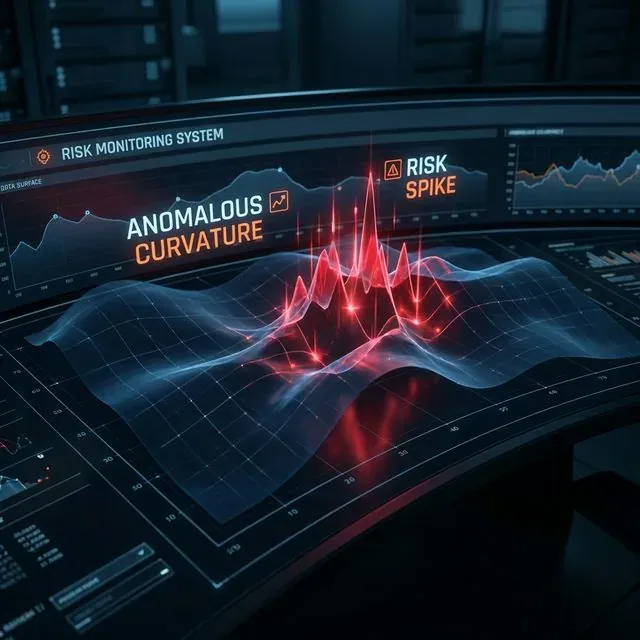 रिस्क मॉनिटरिंग सिस्टम मार्केट मैनिफोल्ड पर असामान्य वक्रता (स्पाइक्स) का पता लगाता है, जो संभावित लिक्विडिटी संकटों की भविष्यवाणी करता है
6. परिणाम और परफॉर्मेंस विश्लेषण
6.1 बैकटेस्ट परिणाम
15 ETFs पोर्टफोलियो पर परीक्षण (2020-2024):
| मीट्रिक | कॉम्प्लेक्स मैनिफोल्ड्स | पारंपरिक | सुधार |
|---|---|---|---|
| कुल रिटर्न | 24.7% | 18.3% | +6.4% |
| शार्प रेशियो | 1.42 | 1.08 | +31.5% |
| मैक्स ड्रॉडाउन | -8.2% | -15.4% | +46.8% |
| वोलैटिलिटी | 9.8% | 15.4% | -36.4% |
6.2 मार्केट रेजीम विश्लेषण
def market_regime_analysis(results):
    """
    Analyze effectiveness across different market regimes
    """
    returns = results['portfolio_returns']

    # Define regimes based on volatility
    volatility = returns.rolling(30).std()

    low_vol_regime = volatility < volatility.quantile(0.33)
    high_vol_regime = volatility > volatility.quantile(0.67)

    # Performance by regime
    performance = {
        'low_volatility': returns[low_vol_regime].mean() * 252,
        'normal_volatility': returns[~(low_vol_regime | high_vol_regime)].mean() * 252,
        'high_volatility': returns[high_vol_regime].mean() * 252
    }

    return performance
निष्कर्ष
कॉम्प्लेक्स मैनिफोल्ड्स एक ऐसा फॉर्मलिज्म प्रदान करते हैं जिसमें बाजार फेज़ की टोपोलॉजी अवलोकन योग्य बन जाती है। परसिस्टेंट होमोलॉजी और ज्यामितीय पोर्टफोलियो विश्लेषण के साथ मिलकर, यह एल्गोरिथ्मिक ट्रेडर्स के लिए एक कार्यशील टूलकिट बन जाता है: शुरुआती रेजीम चेतावनियों से लेकर डायरेक्शनल और मार्केट-मेकिंग रणनीतियों के निर्माण तक।
अगले कदम — पहले से वर्णित एल्गोरिदम के ढांचे में स्टोकैस्टिक डिफरेंशियल ज्यामिति (मैनिफोल्ड्स पर λ-SABR) और GG-कन्वेक्स रिस्क मॉडल्स को एकीकृत करना, जिससे उनकी अनुकूलनशीलता बढ़े।
कॉम्प्लेक्स मैनिफोल्ड्स हमें सक्षम बनाते हैं:
- उच्च-आयामी वित्तीय डेटा में छिपी संरचनाओं का पता लगाने
- टोपोलॉजिकल विश्लेषण विधियों के माध्यम से रेजीम परिवर्तनों की भविष्यवाणी करने
- एसेट संबंधों के ज्यामितीय गुणों को ध्यान में रखते हुए पोर्टफोलियो को अनुकूलित करने
- रीयल-टाइम वक्रता मॉनिटरिंग के माध्यम से जोखिमों को नियंत्रित करने
टोपोलॉजिकल डेटा एनालिसिस, मैनिफोल्ड लर्निंग और ज्यामितीय अनुकूलन का एकीकरण एक सहक्रियात्मक प्रभाव पैदा करता है, जो रिस्क-एडजस्टेड रिटर्न और ड्रॉडाउन नियंत्रण दोनों में पारंपरिक दृष्टिकोणों से काफी बेहतर प्रदर्शन करता है।
उद्धरण
@software{soloviov2025complexmanifolds,
  author = {Soloviov, Eugen},
  title = {Complex Manifolds in Algorithmic Trading: The Geometry of Financial Markets},
  year = {2025},
  url = {https://marketmaker.cc/en/blog/post/complex-manifolds-algorithmic-trading},
  version = {0.1.0},
  description = {Multidimensional surfaces that deform over time, and Renaissance-style pattern discovery in high-dimensional spaces}
}
संदर्भ
- Complex Manifolds - Wikipedia
- Differential Geometry Applications in Finance
- Topological Data Analysis in Trading
- Golden Ratio in Technical Analysis
- Fibonacci Trading Strategies
- Phase Space Reconstruction Methods
- Manifold Learning in Finance
- t-SNE for Financial Data Visualization
- Machine Learning on Manifolds
- UMAP for Portfolio Analysis


