164 articles on algorithmic trading. Filter by topic, follow a collection or press ⌘K to search.
164 articles
Prerequisite: Average, Spread and the Z-Score
Prerequisite: Graphs and Shortest Paths on Your Fingers
Prerequisite: Logarithms, Or Why Bots Add Instead of Multiply
Release: Show Your Bot to People
Pairs Trading From Zero: Two Coins on a Leash
Futures Against Spot: Earning the Funding Rate
Speed: Vectors, Matrices and a Little Rust
Paper Trading, Config and Risk Limits
Reality Check: What Breaks Between the Plan and the Money
How Much Can You Trade? Size, Fees and Slippage
Reading and Walking an Order Book
RICH From Zero: Short Profitable Circles With Colour Coding
SPFA From Zero: The Lazy Version of Bellman-Ford
Bellman-Ford From Zero: Finding a Negative Cycle
Rates as a Graph: Why Arbitrage Becomes a Negative Cycle
Comparing Best Prices: Stage 1 on Five Exchanges
Stages of an Arbitrage System: Designing the Bot
Kinds of Arbitrage: Pick the Type of Your Bot
What Arbitrage Is: Your First Scanner in 10 Minutes
+702% on SOL. Where Is Jev in This Backtest?
XGBoost for Return Direction: Class Imbalance and Decision Thresholds
Transfer Entropy: Which Way Does Information Flow Between Crypto Assets?
Trade Classification When You Have No Side Flag: Tick, Quote, Lee-Ready, BVC
Irregular Time in Tick Models: Continuous-Time Encodings vs. Plain Positional Embeddings
Synthetic Control Methods for Evaluating Trading Strategies
Scoring Probabilistic Forecasts: CRPS, PIT Calibration, and DeepAR
Physics-Informed Neural Networks for Options Pricing
PCMCI: Causal Discovery in Multivariate Crypto Time Series
Order Flow Imbalance: The Cont-Kukanov-Stoikov Event Decomposition
Neural ODEs: Does Continuous Time Beat a Delta-Time Feature?
Multi-Task Learning for Simultaneous Price, Volume, and Volatility Prediction
Model Pruning for Low-Latency Trading Inference
Updating the Volume Curve Intraday: Does Adaptive Forecasting Actually Help?
Koopman Operators and DMD: Do Market Modes Survive Out-of-Sample?
Knowledge Distillation: Compressing Trading Models for Low-Latency Deployment
The Other Way a Regression Lies: Endogeneity, 2SLS, and the Gamma Calibration Problem
Hawkes Processes for Order Arrival and Market Event Modeling
Hamiltonian Neural Networks: Does a Financial System Conserve Anything?
Toda-Yamamoto vs Differenced Granger: Does the BTC Lead-Lag Survive?
Gaussian Processes for Non-Parametric Price Modeling
Fourier Neural Operator for PDE-Based Financial Modeling
Does a Full-Day Context Beat a Ten-Minute One? Flash Attention and the Sequence-Length Question
Ensemble Methods: Combining Weak Learners for Robust Alpha
Double Machine Learning: Estimating a Causal Parameter Instead of Predicting Returns
Causal Forests for Heterogeneous Treatment Effects in Trading
Epistemic vs Aleatoric: Measuring What a Return Model Doesn't Know
AutoML for Systematic Trading Pipelines
Liquidation cascades as a trading signal: reading forced, pre-announced flow
Active Uniswap v3 LPing as Market Making: Range Selection, Rebalancing, and Delta Hedging
The MEV supply chain: PBS, MEV-Boost, and who actually captures the value
On-chain arbitrage: atomic cycles, flash loans, and the auction you have to win
Impermanent Loss and LVR: the real math of LP profitability
Inside the slice: child-order tactics between your scheduler and the exchange
Slippage curves, not slippage constants: cost models that survive contact with live trading
Smart Order Routing in Crypto: One Order, Twelve Venues, No NBBO
The maker-taker decision: fee tiers, rebates, and the true cost of crossing the spread
Implementation shortfall and DIY TCA: measuring what execution actually costs you
Liquidations on-chain: Aave and Compound mechanics, and the bot business around them
Uniswap v3 for Quants: Concentrated Liquidity and Tick Math from First Principles
MEV anatomy: sandwiches, frontrunning, and the dark forest of the mempool
Fill simulation: the ladder from close-price fantasy to queue-aware reality
TWAP vs VWAP vs POV: picking an execution benchmark (and knowing when each lies to you)
Almgren-Chriss Without the Hand-Waving: Optimal Execution You Can Implement in an Afternoon
Volatility Targeting and Trading with GARCH Forecasts
DCC-GARCH: Dynamic Correlations for Pairs and Portfolio Risk
Asymmetric and Heavy-Tailed GARCH: EGARCH, GJR, and Student-t
GARCH(1,1): Forecasting Crypto Volatility
The Honest Negative: Tens of Thousands of Backtests, Five Majors, No Robust Edge
Proving No Look-Ahead in Multi-Timeframe Backtests: Perturb the Future, Prove the Past Can't See It
When the GPU Pays Off: The Parameter-Sweep Roofline, Where a Headline 167x Is Really 27x Algorithm Times 6.2x Hardware
The GPU Precision Trap: How an fp32 Backtest on Apple Metal Silently Returns Garbage
The Fidelity Gate: Coarse-to-Fine Backtesting Fools You Faster Unless the Cheap Proxy Ranks Like the Expensive One
Random vs Smart Search: The Crossover Is Eval Cost, Not the Algorithm
The Two-Axis Parameter Space: Why Most of Your Sweep Should Be Nearly Free
The Framework Tax: When Your Backtest Library Is Slower Than a Naive Pandas Loop
The Probability of Backtest Overfitting: Did Your Search Beat a Coin Flip?
The IPC Tax: Put the Backtest Engine Behind a Socket and Lose 13% - Almost None of It to the Socket
The Deflated Sharpe Ratio: How Many of Your Backtest 'Winners' Survive Multiple Testing?
Objective-Function Design: The Metric You Optimize Secretly Picks Your Strategy
Look-Ahead Bias: How a One-Bar Mistake Manufactures a Sharpe of 15 From Pure Noise
The Backtest Speed Ladder: 298x on a Laptop CPU, Identical PnL to the Last Trade
researcher: A Searchable Quant-Research Archive for Humans and AI Agents
algo-investor-skills: Claude Code Skills That Build a Scam-Proof Investor Proposal
The Kelly Criterion for Strategies: How to Size Positions and Allocate Capital
Daily Stock Analysis: An AI System That Turns a Watchlist Into a Daily Decision Dashboard
Temporal Fusion Transformers for Multi-Horizon Portfolio Forecasting
Conformal Prediction for Risk-Aware Position Sizing
Bid-Ask Spread Modeling and Prediction with Machine Learning
DeepLOB: Deep Learning on Limit Order Books
Inside Our House Algorithm: HRP + Long/Short + CVaR with Hull-White
12 Portfolio Optimization Algorithms, Compared: HRP, Black-Litterman, NCO and Beyond
OneTick: The Platform Where Exchanges Catch Spoofers and Hedge Funds Hunt Alpha
TradingAgents: Multi-Agent AI Framework That Models a Hedge Fund
Prediction Market Arbitrage: Hidden Costs, Fees, and the Real Math
T-Bricks (Broadridge): How the Platform Powering Prop Firms Works
Flowsurface: Open-Source Orderflow Platform for Crypto Markets
Fincept Terminal: Open-Source Bloomberg Terminal Alternative Built on C++ and AI
AutoHedge: A Review of an Autonomous AI Hedge Fund Based on Swarm Intelligence
Kronos: A Foundation Model That Teaches Candlestick Charts to Speak Transformer Language
Jesse: Crypto Algo-Trading Framework with a Minute-Based Engine in Python and Rust
AI Hedge Fund: A Multi-Agent Fund Where AI Analysts Vote on Trades
AI4Finance Foundation: The FinGPT, FinRL, and FinRobot Ecosystem for Algo-Trading
VectorBT: The Fastest Backtesting Framework for Python
Copula Models for Joint Risk Modeling in Crypto Portfolios
ZigBolt: Why We Built Our Own Aeron in Zig and Hit 20 Nanoseconds Per Message
Automated ETF Portfolio Rebalancing: How We Built a Bot for Tinkoff Invest
Aeron: Inside the Messaging System That Powers Half of the HFT Industry
How to Catch Drops After Shitcoin Pumps: A Systematic Approach
Order Types in Algorithmic Trading: From Limit with Chasing to Virtual Orders
Bar Types and Aggregation Methods for Algorithmic Trading
Hidden Markov Models in Trading: How to Adapt Your Strategy to Market Regimes
Queue Inside the Wall: Analyzing Order Position in Order Book Density
LLM Alpha Mining: How to Extract Trading Signals from Earnings Calls and Financial Documents
Statistical Arbitrage and Pairs Trading in Crypto Markets: From Cointegration to the Kalman Filter
Digital Fingerprint of a Trader: How to Identify a Market Maker by Their Order Book Behavior
PnL by Active Time: The Metric That Changes Strategy Rankings
Adaptive Drill-Down: Backtest with Variable Granularity from Minutes to Raw Trades
Aggregated Parquet Cache: How to Speed Up Multi-Timeframe Backtests by Hundreds of Times
Walk-Forward Optimization: The Only Honest Strategy Test
Signal Correlation: How Many Pairs to Monitor
Polars vs Pandas for Algotrading: Benchmarks on Real Data
Plateau Analysis: How to Distinguish a Robust Optimum from Overfitting
Coordinate Descent vs Bayesian Optimization: Which Finds Better Parameters
Multi-Symbol Validation: Test Your Strategy on All Pairs
Funding Rates Kill Your Leverage: Why PnL×50x Is a Fiction
Cascade Strategies: Priority Execution with Fallback Filling
Backtest-live parity: why your bot trades differently from the backtest
Monte Carlo Bootstrap: How to Get Confidence Intervals for a Backtest in 10 Lines of Code
Funding Rate Arbitrage Across Exchanges: How to Profit from Rate Differences
QuestDB for Algorithmic Trading: SQL Extensions That Change the Game
QuestDB for Algorithmic Trading: From Order Books to Production Architecture
QuestDB for Algorithmic Trading: Architecture That Speaks the Language of Markets
Data Communication in Algo Trading Systems: A Technology Overview
Loss-Profit Asymmetry: The Math That Kills Your Deposit
Complex Arbitrage Execution in Rust: From Nanoseconds to Atomic Multi-Legs
GNN, Transformers, and RL for Arbitrage: When Neural Networks Learn to Trade
Matrices, Tensors, and Tropical Algebra: Linear Algebra for Arbitrage Detection
Vine Copulas for Arbitrage: Modeling High-Dimensional Dependencies
Futures-Spot Arbitrage: From Cash-and-Carry to DeFi-CeFi
Graph Algorithms for Arbitrage Detection: From Bellman-Ford to RICH
The Black-Scholes Formula: Option Mathematics and the Holy Grail of Trading
Anomaly Detection for Trading Bot Protection: From Z-Score to Transformer
Markowitz Portfolio Theory for Crypto: From Zero to Hero
From Turbulence to Trading: How Navier-Stokes Equations Revolutionize Algorithmic Trading
The Navier-Stokes Problem: Why Your Coffee Cup Could Run Doom
Trading Signals: Why It Doesn't Work the Way You Think
Diffusion Models vs Cryptocurrency Anarchy: Why DDPM Can Predict Bitcoin Crashes Better Than Your Astrologist
Jim Simons: From Differential Geometry to the Most Profitable Algo-Fund in History
Complex Manifolds in Algorithmic Trading: The Geometry of Financial Markets
CCXT: How WebSocket Orderbook Methods Really Work
Bill Williams Fractals: A Simple Tool for Spotting Extremes and Reversals
Attractors in HFT: When Mathematics Meets the Market
Bill Williams: How a Maverick with a Psychology Degree Changed Trading Forever
The Principle of Multiplicative Composition: A Four-Tier Synergy Model in Investment Strategies
Portfolio Balancer: Hierarchical Investment Management System
Dynamically Combining Mean Reversion and Momentum Strategies in Statistical Arbitrage: Mathematical Foundations and Practical Implementation
Distance Approach in Pairs Trading: Implementation and Analysis with Rust
Developing a Simple C++ Scalper Using FAST/FIX: Step-by-Step Guide
The 'Desire Orderbook' Concept: An Innovative Approach to Market Behavior Prediction
Analysis of Trader Behavior Prediction Capabilities in DEX Based on Identification and Modeling
Building a Market Making Algorithm for Crypto Pairs Using the Avellaneda-Stoikov Model
Trading Candles Demystified: How Raw Trades Become the Foundation of Market Analysis
Revolution in Investment Portfolio Management with Agentic AI
Trading System Terminology Dictionary
Prerequisite: Average, Spread and the Z-Score
Prerequisite: Graphs and Shortest Paths on Your Fingers
Prerequisite: Logarithms, Or Why Bots Add Instead of Multiply
Release: Show Your Bot to People
Pairs Trading From Zero: Two Coins on a Leash
Futures Against Spot: Earning the Funding Rate
Speed: Vectors, Matrices and a Little Rust
Paper Trading, Config and Risk Limits
Reality Check: What Breaks Between the Plan and the Money
How Much Can You Trade? Size, Fees and Slippage
Reading and Walking an Order Book
RICH From Zero: Short Profitable Circles With Colour Coding
SPFA From Zero: The Lazy Version of Bellman-Ford
Bellman-Ford From Zero: Finding a Negative Cycle
Rates as a Graph: Why Arbitrage Becomes a Negative Cycle
Comparing Best Prices: Stage 1 on Five Exchanges
Stages of an Arbitrage System: Designing the Bot
Kinds of Arbitrage: Pick the Type of Your Bot
What Arbitrage Is: Your First Scanner in 10 Minutes
+702% on SOL. Where Is Jev in This Backtest?

XGBoost for Return Direction: Class Imbalance and Decision Thresholds
Transfer Entropy: Which Way Does Information Flow Between Crypto Assets?
Trade Classification When You Have No Side Flag: Tick, Quote, Lee-Ready, BVC

Irregular Time in Tick Models: Continuous-Time Encodings vs. Plain Positional Embeddings

Synthetic Control Methods for Evaluating Trading Strategies

Scoring Probabilistic Forecasts: CRPS, PIT Calibration, and DeepAR
Physics-Informed Neural Networks for Options Pricing
PCMCI: Causal Discovery in Multivariate Crypto Time Series
Order Flow Imbalance: The Cont-Kukanov-Stoikov Event Decomposition

Neural ODEs: Does Continuous Time Beat a Delta-Time Feature?

Multi-Task Learning for Simultaneous Price, Volume, and Volatility Prediction

Model Pruning for Low-Latency Trading Inference
Updating the Volume Curve Intraday: Does Adaptive Forecasting Actually Help?

Koopman Operators and DMD: Do Market Modes Survive Out-of-Sample?

Knowledge Distillation: Compressing Trading Models for Low-Latency Deployment
The Other Way a Regression Lies: Endogeneity, 2SLS, and the Gamma Calibration Problem

Hawkes Processes for Order Arrival and Market Event Modeling

Hamiltonian Neural Networks: Does a Financial System Conserve Anything?
Toda-Yamamoto vs Differenced Granger: Does the BTC Lead-Lag Survive?

Gaussian Processes for Non-Parametric Price Modeling

Fourier Neural Operator for PDE-Based Financial Modeling

Does a Full-Day Context Beat a Ten-Minute One? Flash Attention and the Sequence-Length Question

Ensemble Methods: Combining Weak Learners for Robust Alpha

Double Machine Learning: Estimating a Causal Parameter Instead of Predicting Returns

Causal Forests for Heterogeneous Treatment Effects in Trading

Epistemic vs Aleatoric: Measuring What a Return Model Doesn't Know

AutoML for Systematic Trading Pipelines
Liquidation cascades as a trading signal: reading forced, pre-announced flow
Active Uniswap v3 LPing as Market Making: Range Selection, Rebalancing, and Delta Hedging
The MEV supply chain: PBS, MEV-Boost, and who actually captures the value
On-chain arbitrage: atomic cycles, flash loans, and the auction you have to win
Impermanent Loss and LVR: the real math of LP profitability
Inside the slice: child-order tactics between your scheduler and the exchange

Slippage curves, not slippage constants: cost models that survive contact with live trading

Smart Order Routing in Crypto: One Order, Twelve Venues, No NBBO

The maker-taker decision: fee tiers, rebates, and the true cost of crossing the spread

Implementation shortfall and DIY TCA: measuring what execution actually costs you
Liquidations on-chain: Aave and Compound mechanics, and the bot business around them
Uniswap v3 for Quants: Concentrated Liquidity and Tick Math from First Principles
MEV anatomy: sandwiches, frontrunning, and the dark forest of the mempool
Fill simulation: the ladder from close-price fantasy to queue-aware reality

TWAP vs VWAP vs POV: picking an execution benchmark (and knowing when each lies to you)

Almgren-Chriss Without the Hand-Waving: Optimal Execution You Can Implement in an Afternoon

Volatility Targeting and Trading with GARCH Forecasts

DCC-GARCH: Dynamic Correlations for Pairs and Portfolio Risk

Asymmetric and Heavy-Tailed GARCH: EGARCH, GJR, and Student-t

GARCH(1,1): Forecasting Crypto Volatility

The Honest Negative: Tens of Thousands of Backtests, Five Majors, No Robust Edge

Proving No Look-Ahead in Multi-Timeframe Backtests: Perturb the Future, Prove the Past Can't See It
When the GPU Pays Off: The Parameter-Sweep Roofline, Where a Headline 167x Is Really 27x Algorithm Times 6.2x Hardware
The GPU Precision Trap: How an fp32 Backtest on Apple Metal Silently Returns Garbage
The Fidelity Gate: Coarse-to-Fine Backtesting Fools You Faster Unless the Cheap Proxy Ranks Like the Expensive One
Random vs Smart Search: The Crossover Is Eval Cost, Not the Algorithm
The Two-Axis Parameter Space: Why Most of Your Sweep Should Be Nearly Free
The Framework Tax: When Your Backtest Library Is Slower Than a Naive Pandas Loop

The Probability of Backtest Overfitting: Did Your Search Beat a Coin Flip?

The IPC Tax: Put the Backtest Engine Behind a Socket and Lose 13% - Almost None of It to the Socket

The Deflated Sharpe Ratio: How Many of Your Backtest 'Winners' Survive Multiple Testing?

Objective-Function Design: The Metric You Optimize Secretly Picks Your Strategy
Look-Ahead Bias: How a One-Bar Mistake Manufactures a Sharpe of 15 From Pure Noise

The Backtest Speed Ladder: 298x on a Laptop CPU, Identical PnL to the Last Trade
researcher: A Searchable Quant-Research Archive for Humans and AI Agents

algo-investor-skills: Claude Code Skills That Build a Scam-Proof Investor Proposal

The Kelly Criterion for Strategies: How to Size Positions and Allocate Capital
Daily Stock Analysis: An AI System That Turns a Watchlist Into a Daily Decision Dashboard
Temporal Fusion Transformers for Multi-Horizon Portfolio Forecasting
Conformal Prediction for Risk-Aware Position Sizing
Bid-Ask Spread Modeling and Prediction with Machine Learning
DeepLOB: Deep Learning on Limit Order Books

Inside Our House Algorithm: HRP + Long/Short + CVaR with Hull-White

12 Portfolio Optimization Algorithms, Compared: HRP, Black-Litterman, NCO and Beyond
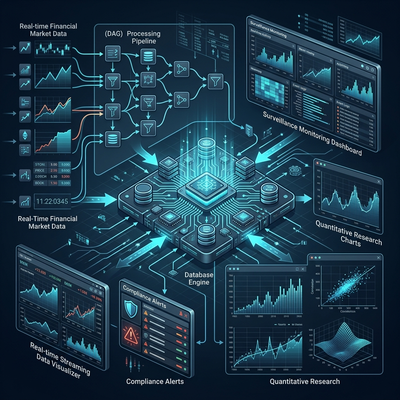
OneTick: The Platform Where Exchanges Catch Spoofers and Hedge Funds Hunt Alpha
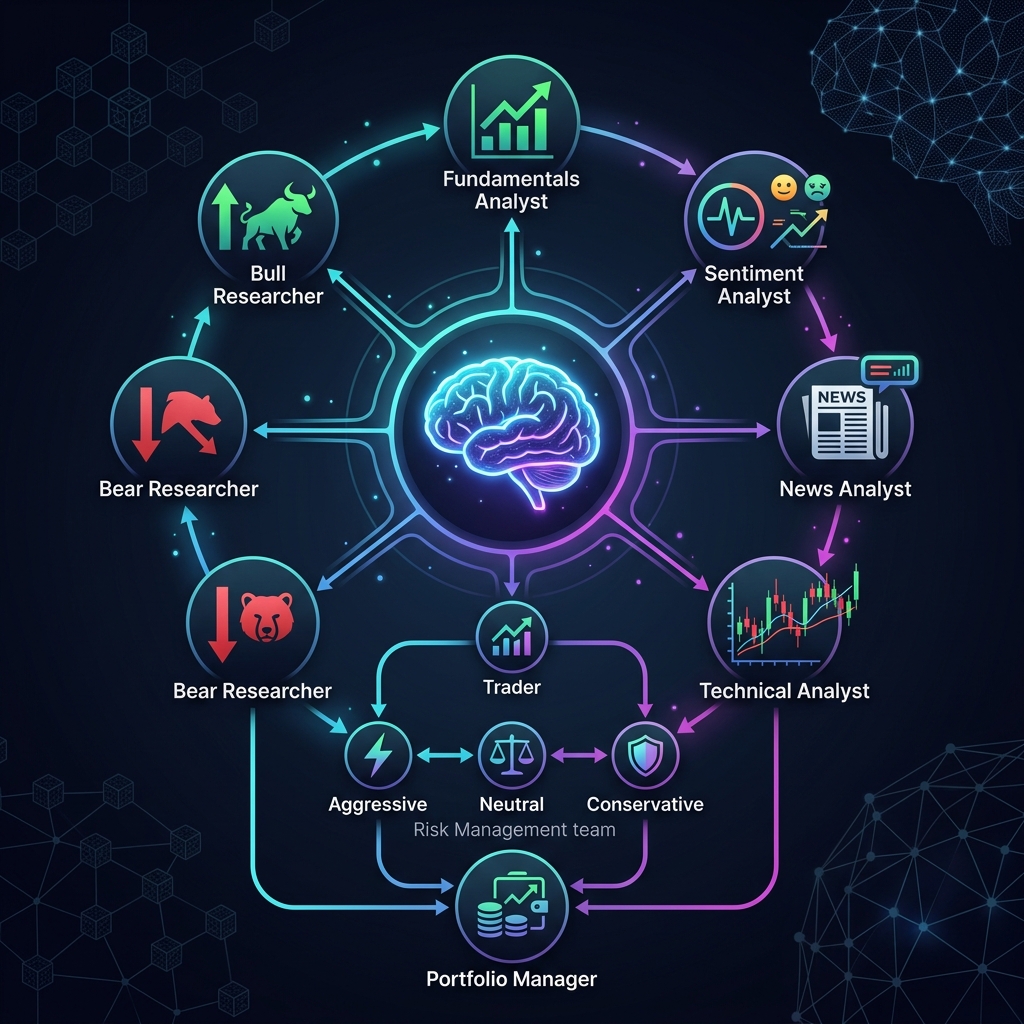
TradingAgents: Multi-Agent AI Framework That Models a Hedge Fund
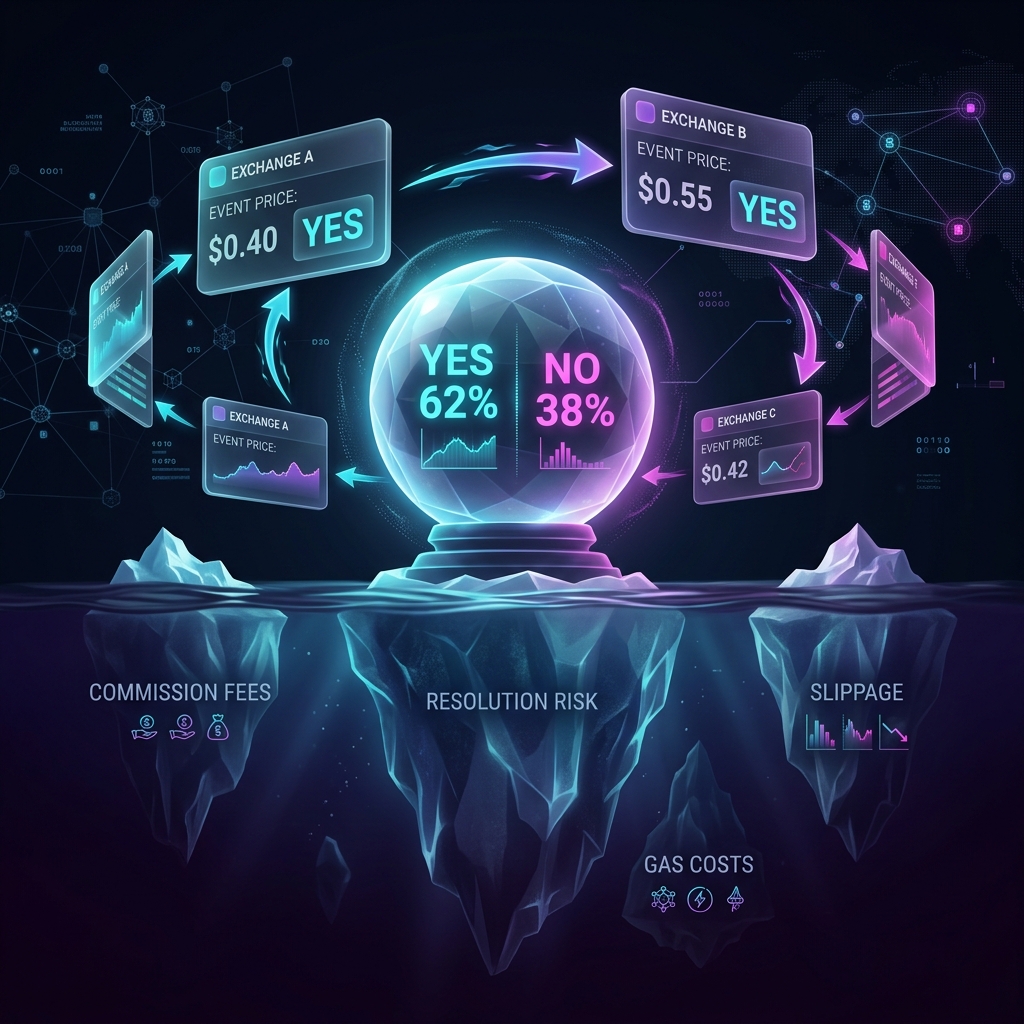
Prediction Market Arbitrage: Hidden Costs, Fees, and the Real Math

T-Bricks (Broadridge): How the Platform Powering Prop Firms Works
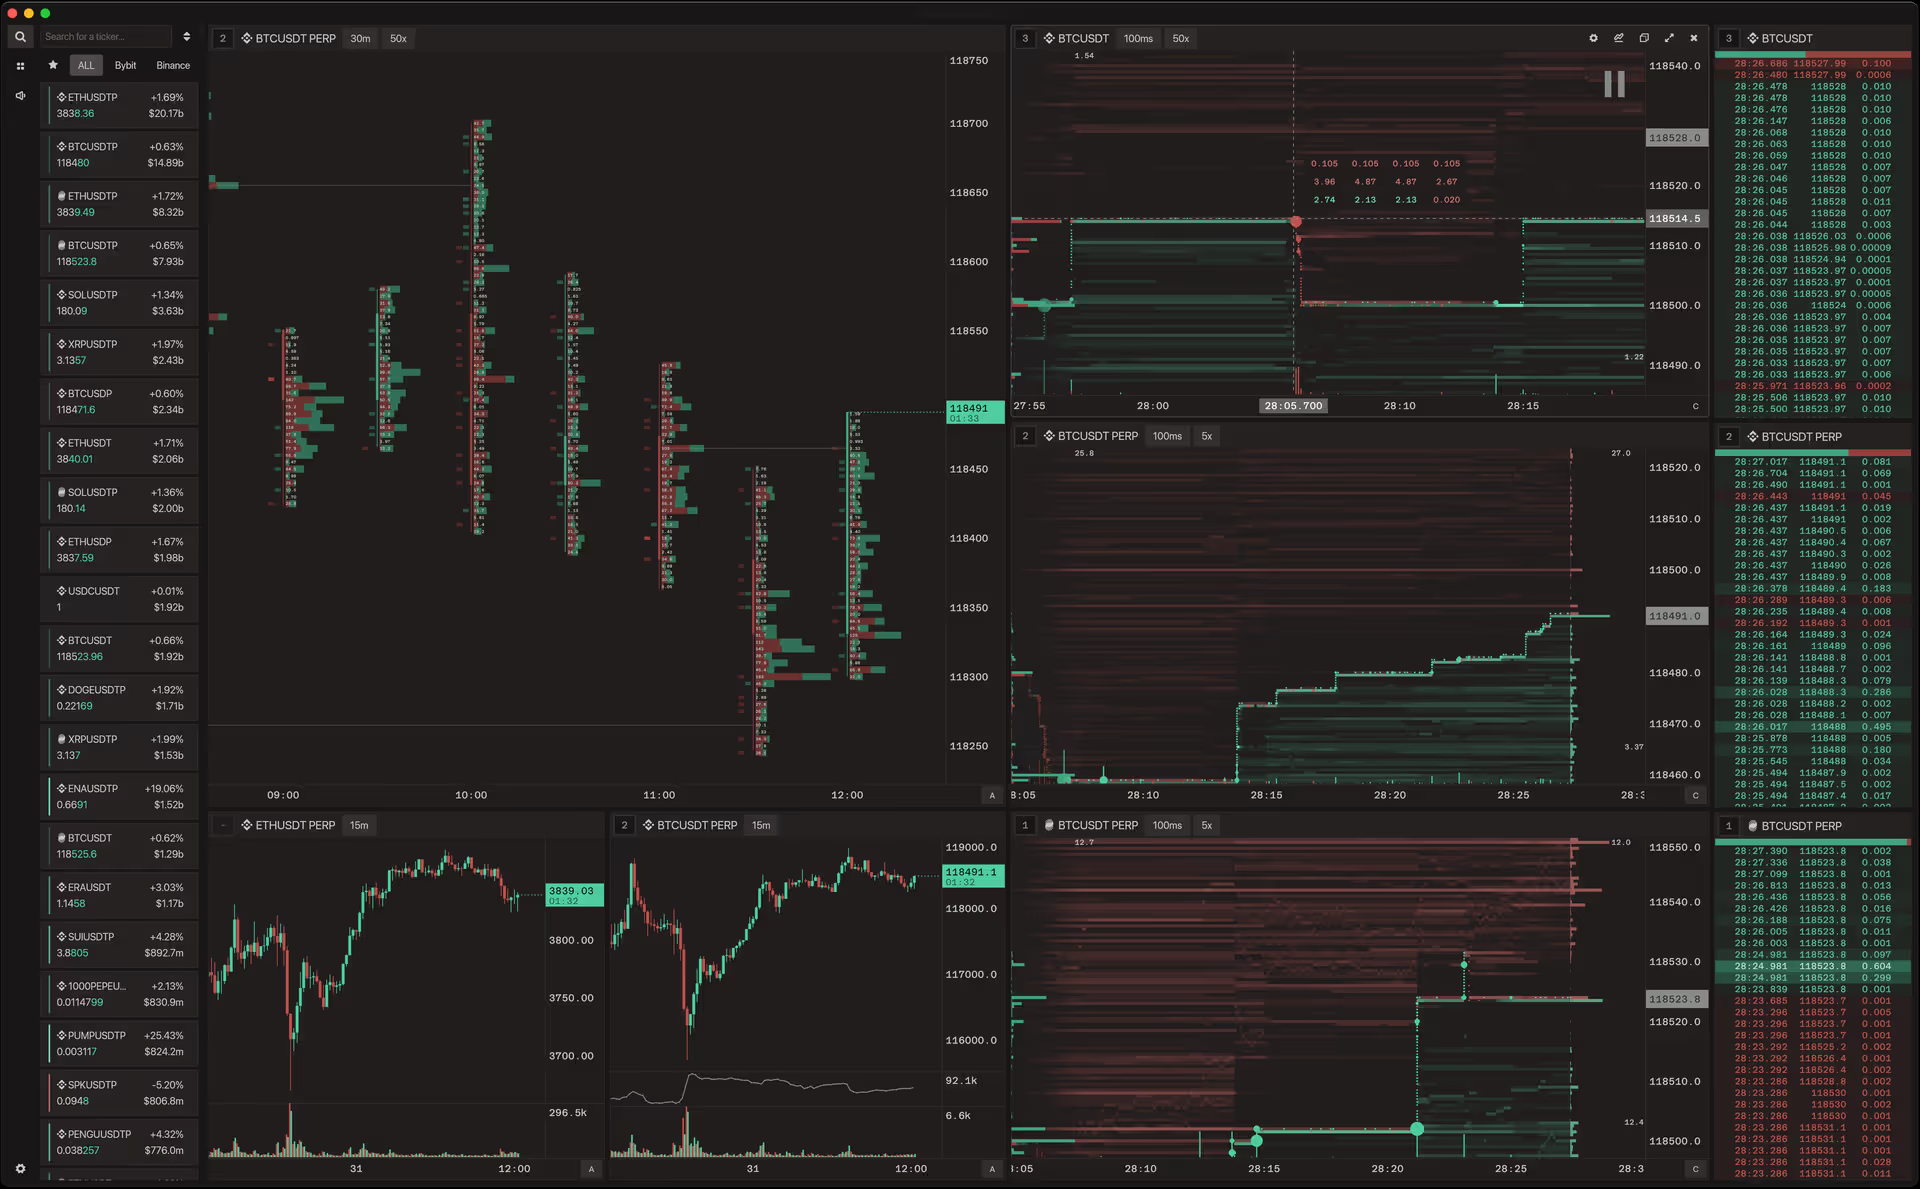
Flowsurface: Open-Source Orderflow Platform for Crypto Markets
Fincept Terminal: Open-Source Bloomberg Terminal Alternative Built on C++ and AI
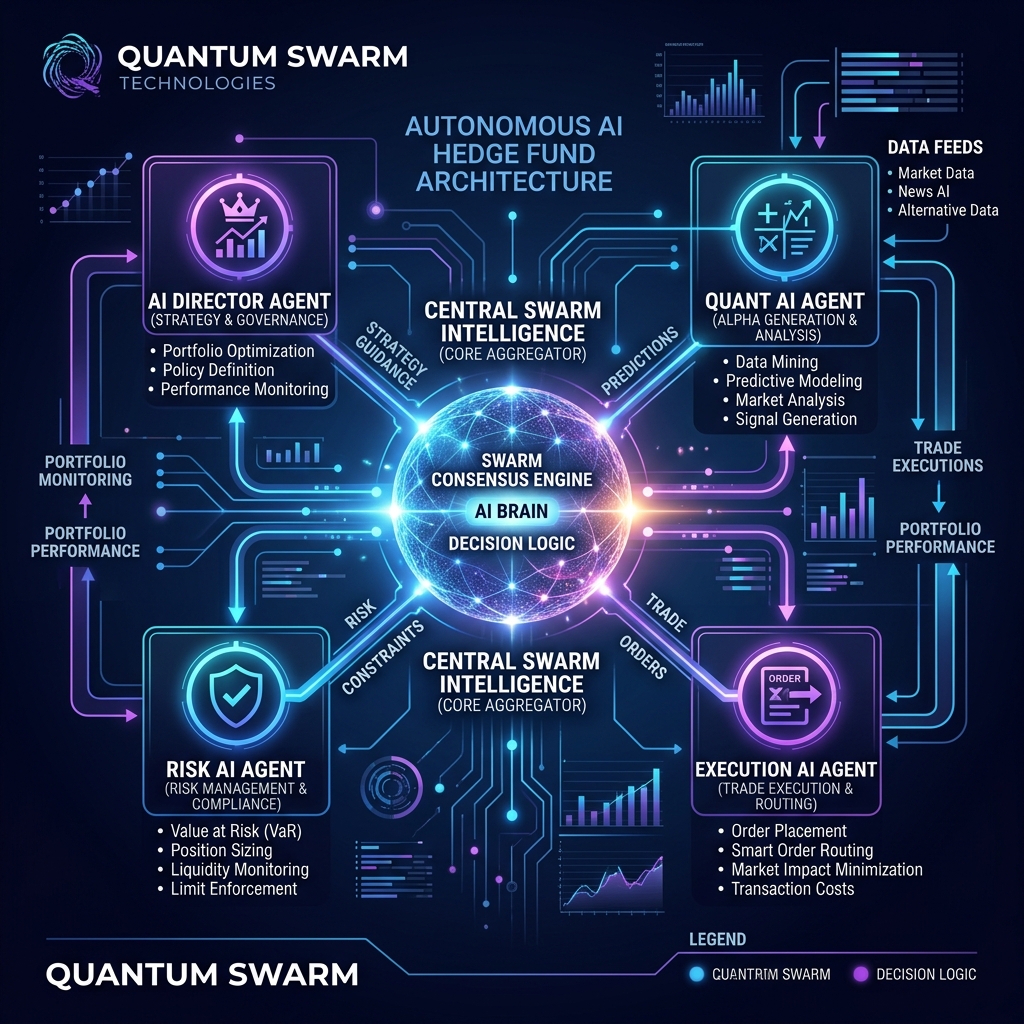
AutoHedge: A Review of an Autonomous AI Hedge Fund Based on Swarm Intelligence
Kronos: A Foundation Model That Teaches Candlestick Charts to Speak Transformer Language

Jesse: Crypto Algo-Trading Framework with a Minute-Based Engine in Python and Rust

AI Hedge Fund: A Multi-Agent Fund Where AI Analysts Vote on Trades
AI4Finance Foundation: The FinGPT, FinRL, and FinRobot Ecosystem for Algo-Trading
VectorBT: The Fastest Backtesting Framework for Python

Copula Models for Joint Risk Modeling in Crypto Portfolios
ZigBolt: Why We Built Our Own Aeron in Zig and Hit 20 Nanoseconds Per Message

Automated ETF Portfolio Rebalancing: How We Built a Bot for Tinkoff Invest
Aeron: Inside the Messaging System That Powers Half of the HFT Industry
How to Catch Drops After Shitcoin Pumps: A Systematic Approach
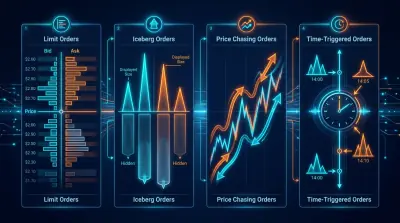
Order Types in Algorithmic Trading: From Limit with Chasing to Virtual Orders
Bar Types and Aggregation Methods for Algorithmic Trading
Hidden Markov Models in Trading: How to Adapt Your Strategy to Market Regimes
Queue Inside the Wall: Analyzing Order Position in Order Book Density
LLM Alpha Mining: How to Extract Trading Signals from Earnings Calls and Financial Documents
Statistical Arbitrage and Pairs Trading in Crypto Markets: From Cointegration to the Kalman Filter
Digital Fingerprint of a Trader: How to Identify a Market Maker by Their Order Book Behavior

PnL by Active Time: The Metric That Changes Strategy Rankings

Adaptive Drill-Down: Backtest with Variable Granularity from Minutes to Raw Trades
Aggregated Parquet Cache: How to Speed Up Multi-Timeframe Backtests by Hundreds of Times
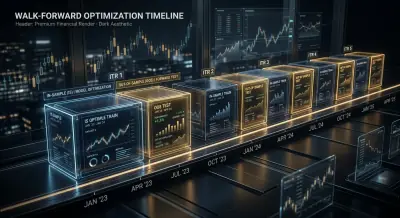
Walk-Forward Optimization: The Only Honest Strategy Test
Signal Correlation: How Many Pairs to Monitor
Polars vs Pandas for Algotrading: Benchmarks on Real Data
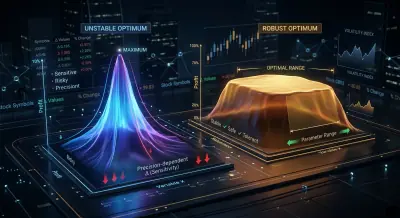
Plateau Analysis: How to Distinguish a Robust Optimum from Overfitting
Coordinate Descent vs Bayesian Optimization: Which Finds Better Parameters

Multi-Symbol Validation: Test Your Strategy on All Pairs

Funding Rates Kill Your Leverage: Why PnL×50x Is a Fiction

Cascade Strategies: Priority Execution with Fallback Filling
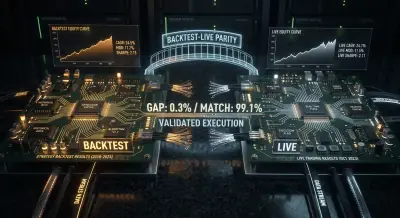
Backtest-live parity: why your bot trades differently from the backtest

Monte Carlo Bootstrap: How to Get Confidence Intervals for a Backtest in 10 Lines of Code
Funding Rate Arbitrage Across Exchanges: How to Profit from Rate Differences
QuestDB for Algorithmic Trading: SQL Extensions That Change the Game
QuestDB for Algorithmic Trading: From Order Books to Production Architecture
QuestDB for Algorithmic Trading: Architecture That Speaks the Language of Markets
Data Communication in Algo Trading Systems: A Technology Overview

Loss-Profit Asymmetry: The Math That Kills Your Deposit
Complex Arbitrage Execution in Rust: From Nanoseconds to Atomic Multi-Legs
GNN, Transformers, and RL for Arbitrage: When Neural Networks Learn to Trade
Matrices, Tensors, and Tropical Algebra: Linear Algebra for Arbitrage Detection
Vine Copulas for Arbitrage: Modeling High-Dimensional Dependencies
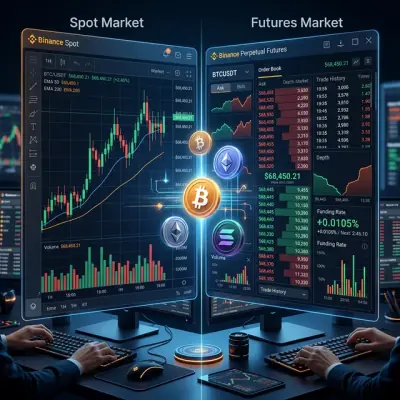
Futures-Spot Arbitrage: From Cash-and-Carry to DeFi-CeFi
Graph Algorithms for Arbitrage Detection: From Bellman-Ford to RICH
The Black-Scholes Formula: Option Mathematics and the Holy Grail of Trading

Anomaly Detection for Trading Bot Protection: From Z-Score to Transformer

Markowitz Portfolio Theory for Crypto: From Zero to Hero

From Turbulence to Trading: How Navier-Stokes Equations Revolutionize Algorithmic Trading

The Navier-Stokes Problem: Why Your Coffee Cup Could Run Doom
Trading Signals: Why It Doesn't Work the Way You Think

Diffusion Models vs Cryptocurrency Anarchy: Why DDPM Can Predict Bitcoin Crashes Better Than Your Astrologist

Jim Simons: From Differential Geometry to the Most Profitable Algo-Fund in History

Complex Manifolds in Algorithmic Trading: The Geometry of Financial Markets
CCXT: How WebSocket Orderbook Methods Really Work

Bill Williams Fractals: A Simple Tool for Spotting Extremes and Reversals

Attractors in HFT: When Mathematics Meets the Market

Bill Williams: How a Maverick with a Psychology Degree Changed Trading Forever

The Principle of Multiplicative Composition: A Four-Tier Synergy Model in Investment Strategies

Portfolio Balancer: Hierarchical Investment Management System
Dynamically Combining Mean Reversion and Momentum Strategies in Statistical Arbitrage: Mathematical Foundations and Practical Implementation
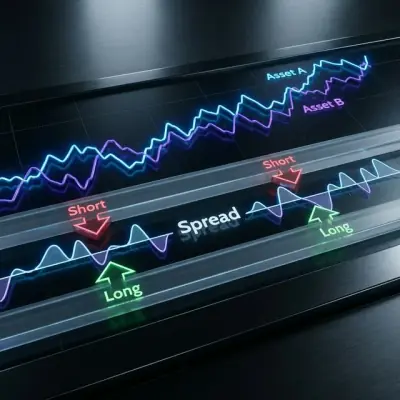
Distance Approach in Pairs Trading: Implementation and Analysis with Rust

Developing a Simple C++ Scalper Using FAST/FIX: Step-by-Step Guide

The 'Desire Orderbook' Concept: An Innovative Approach to Market Behavior Prediction
Analysis of Trader Behavior Prediction Capabilities in DEX Based on Identification and Modeling
Building a Market Making Algorithm for Crypto Pairs Using the Avellaneda-Stoikov Model
Trading Candles Demystified: How Raw Trades Become the Foundation of Market Analysis
Revolution in Investment Portfolio Management with Agentic AI

Trading System Terminology Dictionary
Nothing under this topic yet.Try another topic or clear the filter.