Jesse: Crypto Algo-Trading Framework with a Minute-Based Engine in Python and Rust
In-depth review of Jesse - an algo-trading framework for crypto markets. Minute-based simulation, strategies as state machines, Rust-accelerated indicators, optimization with overfitting protection, and the boundary between open-source core and live trading.
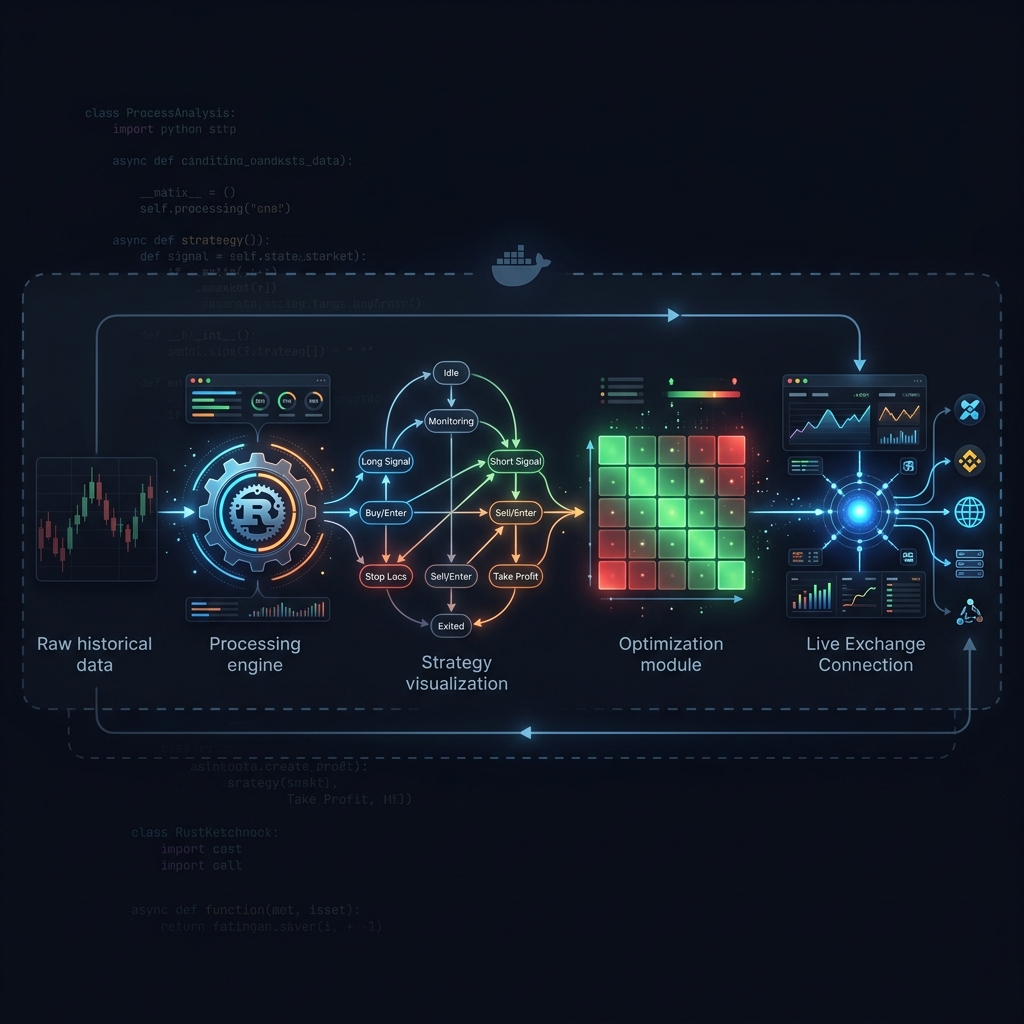

Most open-source backtesting engines fall into two camps: academic stacks that test beautifully but are useless for real trading, and battle-tested terminals that trade but won't let you research properly. Jesse tries to be both — a crypto trading framework with a unified engine for backtesting, optimization, and (via plugin) live trading.
Architecture: Not a Library, but a Pipeline
Jesse is a strategy execution engine + API + UI bundle: CLI starts uvicorn with FastAPI, PostgreSQL via Peewee, LSP for the strategy editor, and optional jesse-live plugin.
Minute-Based Simulation: The "Source of Truth"

A critical invariant: only 1-minute candles are accepted in backtests. Higher timeframes are aggregates — the 1h strategy fires every 60 minutes, but orders execute within each minute by high/low.
from jesse.research import backtest

result = backtest(
    config,
    routes=[("Binance", "BTC-USDT", "4h", "MyStrategy")],
    candles=candles_1m,  # strictly 60_000 ms between candles
)
Strategy: A State Machine with Declarative Orders
def go_long(self):
    qty = utils.size_to_qty(self.balance * 0.5, self.price)
    self.buy = qty, self.price
    self.stop_loss = qty, self.price * 0.97
    self.take_profit = qty, self.price * 1.05
The system decides: market, limit, or stop — based on price position relative to current. In live mode, price is rounded by exchange precision.
Optimization: Cutting Noise, Not Maximizing Profit
Fitness function fights overfitting: minimum 5 trades filter, log-normalized trade count, dual train/test validation, and "smart" Sharpe with autocorrelation penalty.
Rust Under the Hood
Indicators (EMA, RSI, MACD, ATR…) use jesse-rust. Even basic arithmetic is in Rust: float error accumulation over thousands of trades turns backtests into fiction.
Links
- 💻 GitHub: jesse-ai/jesse
- 🌐 Website: jesse.trade
- 📄 License: MIT
Conclusion
Jesse attempts to reduce crypto algo-trading to a repeatable pipeline: minute engine, strict Strategy, Rust indicators, research API without state leaks, optimization with test period validation.