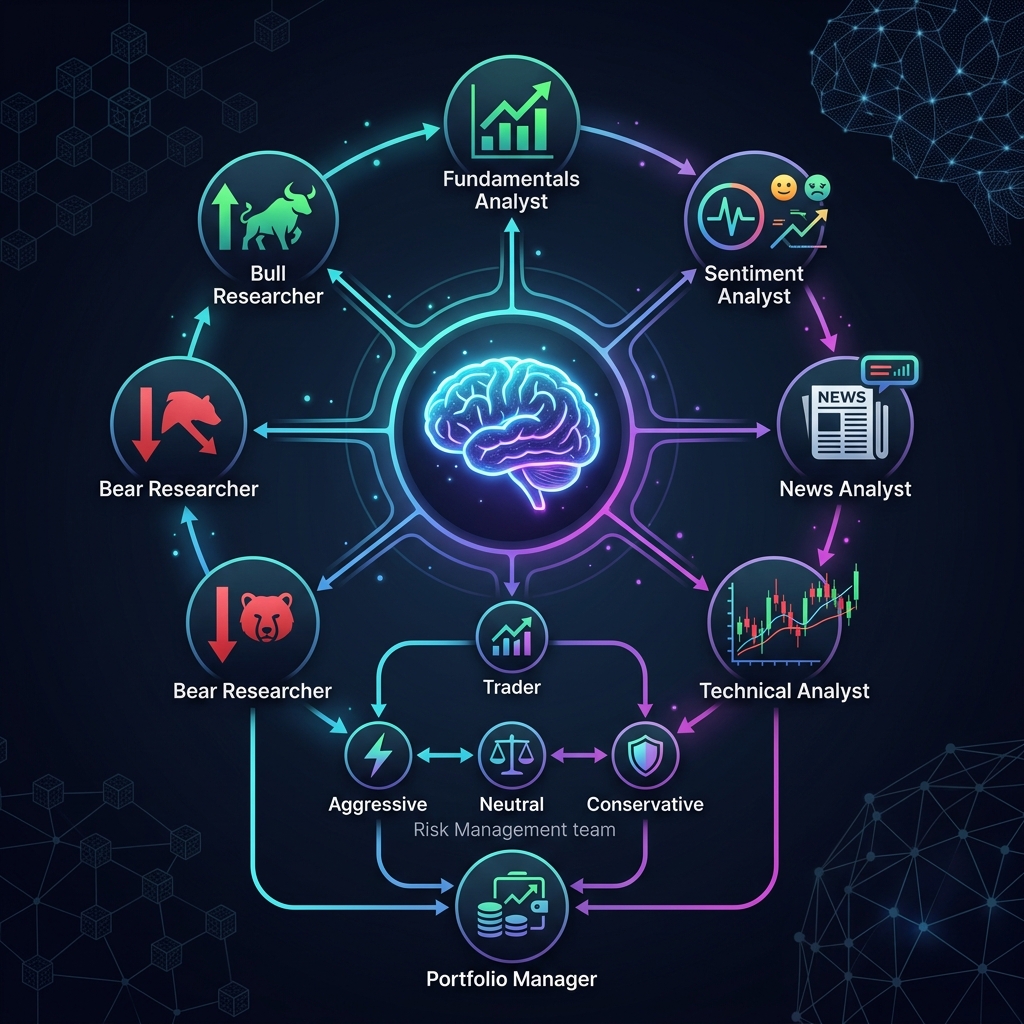

Most AI trading projects are a single LLM fed data and asked to "make a decision." TradingAgents (GitHub, arXiv: 2412.20138) takes a different path: instead of one agent — an entire trading firm staff, where each role is a separate LLM agent with its own tools, data sources, and prompt.
Built on LangGraph, the framework creates a system that doesn't just "look at data" — it debates with itself before making a decision.
Architecture: From Data to Decision

The full pipeline is a directed acyclic graph (DAG) of 12 nodes:
Analyst Team → Research Debate → Trader → Risk Debate → Portfolio Manager → BUY/HOLD/SELL
Analyst Team: Four Specializations
| Agent | Data Sources | Focus |
|---|---|---|
| Fundamentals Analyst | Balance sheet, cashflow, income statement | Intrinsic value vs market price |
| Sentiment Analyst | Yahoo Finance News, StockTwits, Reddit | Multi-source sentiment aggregation |
| News Analyst | Ticker news, macro headlines, insider transactions | Event-driven signals |
| Technical Analyst | OHLCV, MACD, RSI, Bollinger Bands | Pattern detection and momentum |
Research Debate: Bull vs Bear

After analysts produce reports, adversarial debate begins:
- Bull Researcher builds the bullish thesis
- Bear Researcher builds the bearish counter-thesis
- Multi-round debate (configurable via
max_debate_rounds) - Research Manager (deep thinking LLM) synthesizes both positions
Risk Management: Triple Filter
The trader's proposal passes through three risk managers debating each other:
| Agent | Profile |
|---|---|
| Aggressive Analyst | High risk tolerance, upside focus |
| Neutral Analyst | Balanced risk/reward |
| Conservative Analyst | Low risk tolerance, downside protection |
Portfolio Manager: Final Decision
Receives trader proposal + risk debate results + reflective memory from past decisions. Approves, rejects, or adjusts the trade.
Reflective Memory
The system maintains a decision log. On each subsequent run for the same ticker, it fetches realized returns (raw + alpha vs SPY), generates reflections, and injects history into the Portfolio Manager prompt — creating learning from mistakes without fine-tuning.
Tech Stack
| Component | Technology |
|---|---|
| Orchestration | LangGraph (StateGraph, checkpoints) |
| LLM Providers | OpenAI, Google, Anthropic, xAI, DeepSeek, Qwen, Ollama, Azure |
| Market Data | yFinance, Alpha Vantage |
| Social Data | StockTwits API, Reddit API |